

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
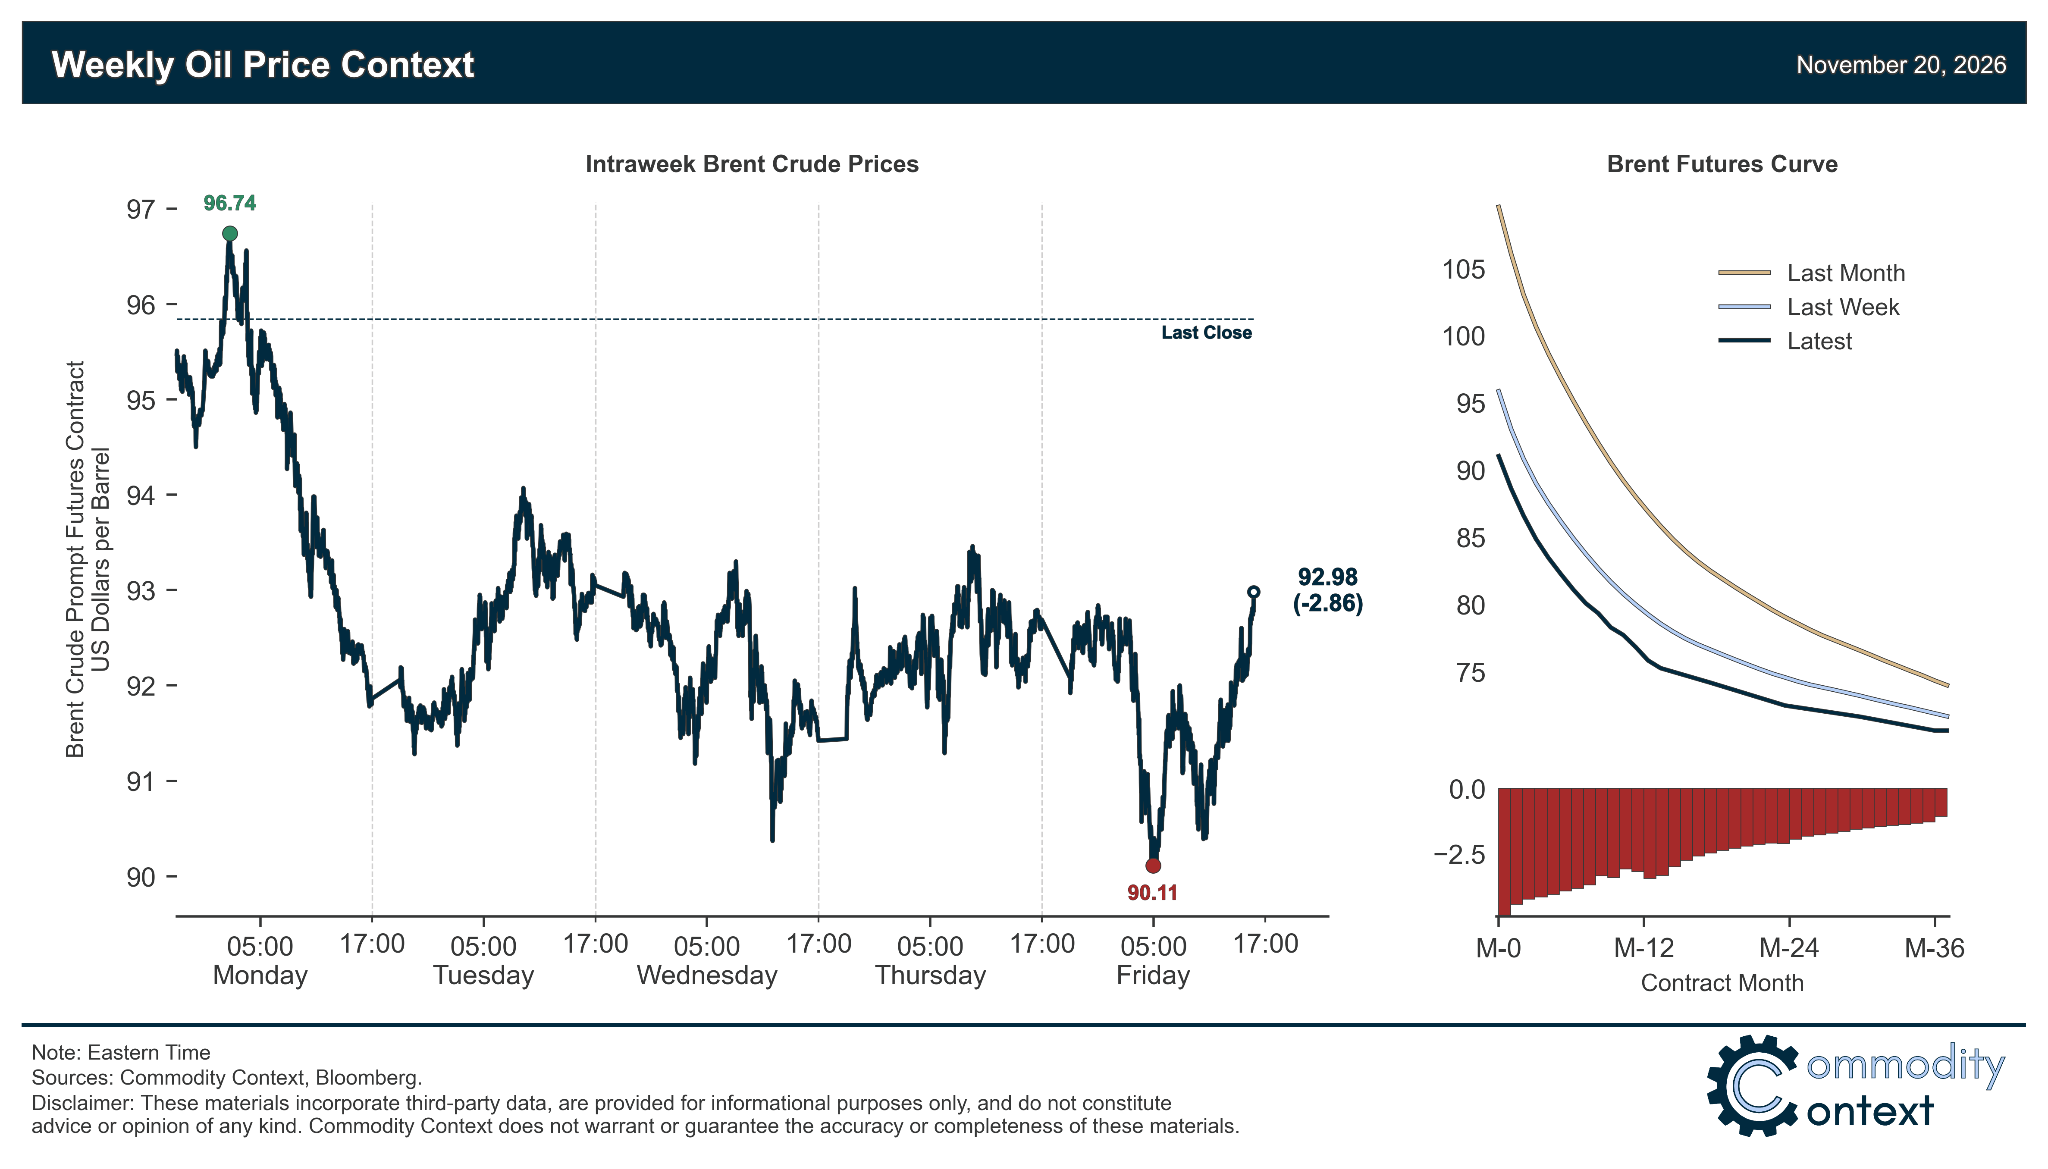
Flat Prices pulled back another ~$3/bbl for Brent to end the week around $93/bbl as the barrel remained battered by the sanguine—and increasingly stale—consensus narrative regarding the recovery in Middle Eastern oil supplies despite heightened security risks, together with the tech-driven risk-off selloff across global equity markets.
Timespreads were flat to lower for major futures curves: Brent spreads traded sideways, WTI backwardation weakened ahead of its December contract expiry, and Dubai fell back through Friday trading; physical markets, however, showed comparative strength as the contango spreading across the physical Brent CFD curve began to correct itself after nearly a month of creeping weakness, and Dated Brent is now back to trading above the prompt Brent futures contract.
Inventories data leaned bearish and all three major commercial hubs have seen inventory levels bounce back from recent depths—each now at the very bottom of the respective trailing 5-year seasonal ranges; US gasoline is especially well-stocked and jet fuel is building counterseasonally but crude and diesel stocks remain very low.
Refined Products prices broadly retreated, with gasoline crack spreads falling below year-ago levels to the trailing 5-year seasonal average for the first time since the beginning of the Iran War as US inventories surge; diesel cracks, too, have fallen to the lowest level since July on the back of the October rise in middle distillate exports, though, critically, the export recovery—across both Russia and India—appears to have faltered over the past week.
Market Positioning data confirmed that speculative positioning in major crude contracts was roughly flat over the past week-through-Tuesday, though delayed CFTC data published Monday confirms the scale of the prior weeks’ spec selloff that brought net Managed Money length to its lowest level since early-July, tilting the balance of positioning risk squarely to the upside and furnishing the market with plenty of kindling to fuel the next rally.
As Well As how to think about the lagged connection between Hormuz export volumes and realized prices; further confirmation of the slowdown in Middle Eastern oil exports as well as steeply lower inbound ballast capacity; Chinese crude imports have set a fresh post-Beijing Swing high-water mark; and a faltering in the recent diesel export recovery.