

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Note that our regular Market Positioning Data Deck is delayed this week due to the CFTC pushing back the publication of its Commitments of Traders data to Monday given the Veterans Day holiday earlier this week.
Heads up that the full Commodity Context team (my family) is out of office next week on a much-needed family vacation, so I will be slower than usual to reply. Please try to avoid re-escalating the Iran War over the next 5 business days.
🎙️ In the latest episode of the Oil Ground Up podcast (video), I was joined by the co-founders of HiLo Analytics to discuss what it’s like building an oil market data company today and how AI agents are changing the way analysts consume data.
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
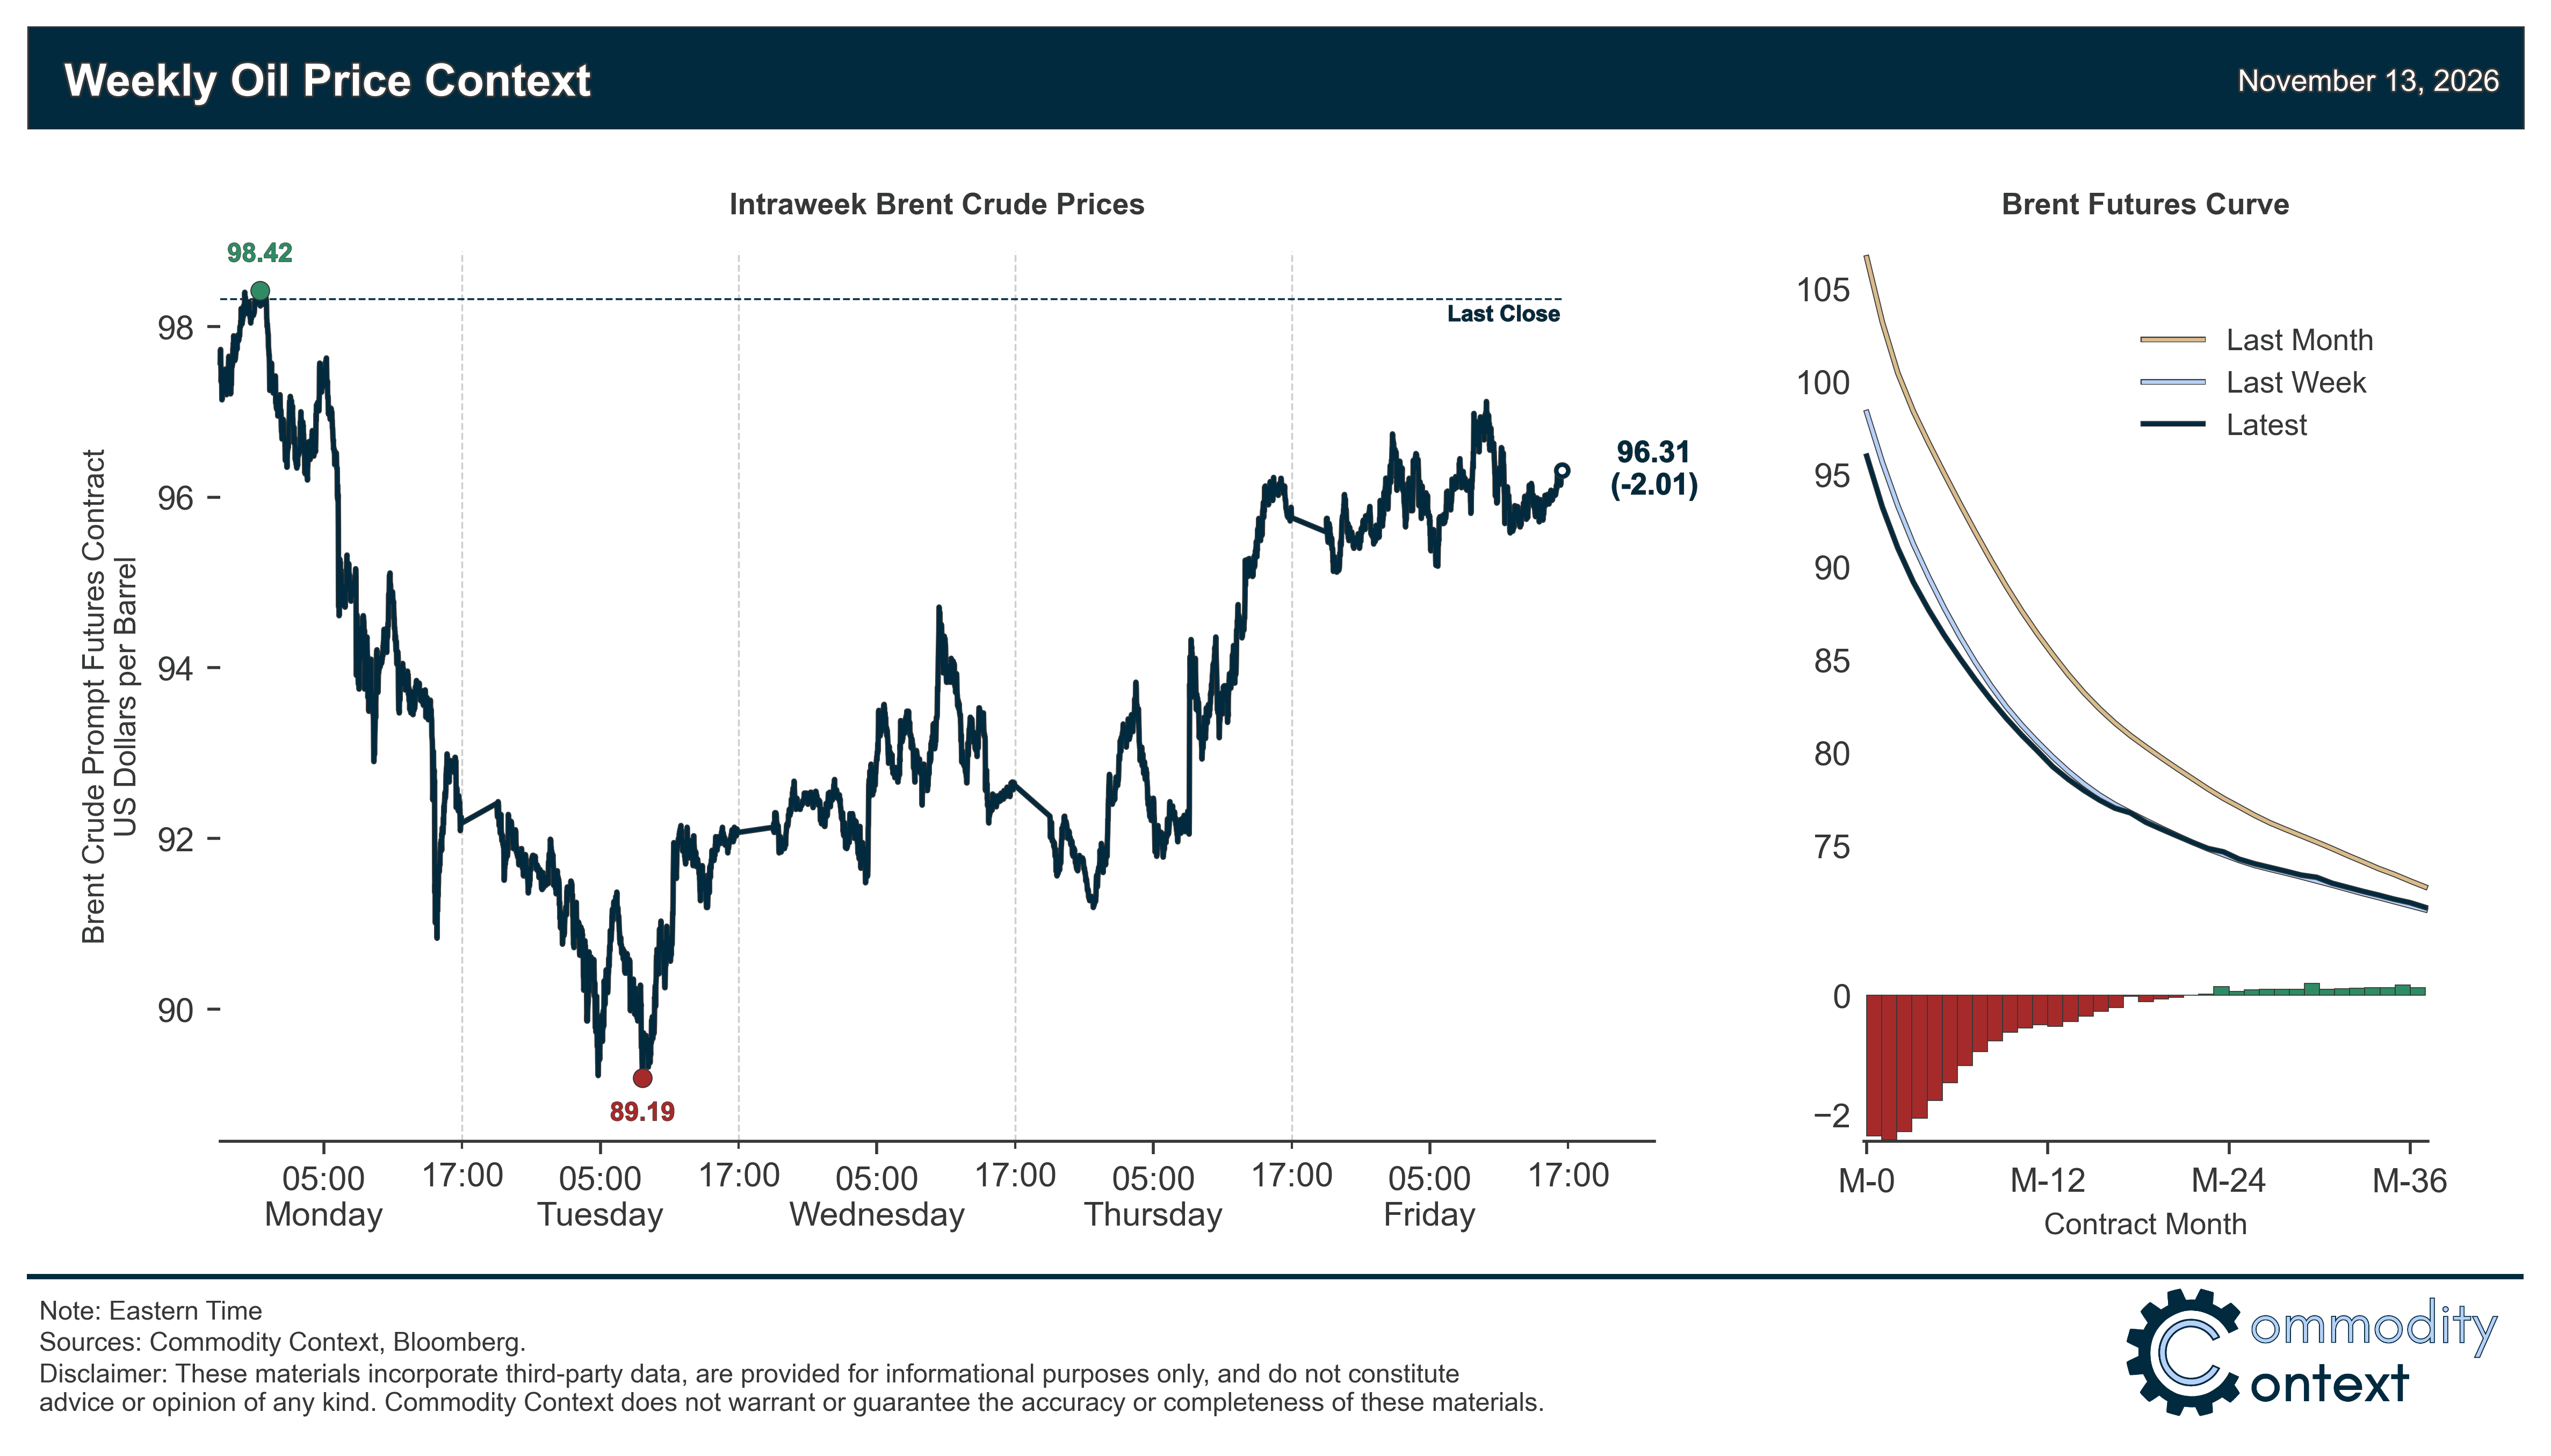
Flat Prices fell ~$2/bbl for Brent to end around $96/bbl amidst the whiplash of scuttled US diplomatic efforts and President Trump indicating a strong preference for a perpetuation of the rocky, volatile status quo.
Timespreads tracked the path of flat prices, slipping through the first half before round-tripping to largely flat by the end of Friday; however, while all major crude futures curves remain solidly backwardated, the Brent CFD curve weakened into broader contango and continues to present the most bearish physical market indicator across a still-precarious market.
Inventories data were bearish as big inflows were recorded across all major tracked storage hubs; together this constitutes one of the largest weekly stock builds since the start of the Iran War, though stock levels remain extremely low.
Refined Products remain sharply split between gasoline and diesel: while gasoline crack spreads fell below 2025 levels as US inventories rose above year-ago levels, diesel cracks remain above $80/bbl and within a tight ~$5/bbl range month-to-date as diesel stocks remain low across all tracked hubs—though Asia inventories of the key industrial fuel are the least depressed relative to the seasonal norm.
Market Positioning data was only published in part this week, with the CFTC delaying publication to Monday due to Veterans Day; data released by ICE indicates that Brent suffered another heavy bout of speculative selling over the past week-through-Tuesday, which brought the net Managed Money position in the ICE Brent contract to its lowest level since the first week of July, when the market was still climbing out of the post-MOU rout.
As Well As can we just muddle through the Iran War status quo(?), the IEA sees oil market flipping to notable supply surplus in October, and initial estimates point to us lurchingly pulling back from peak sustained war-time Hormuz flow in October.