

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
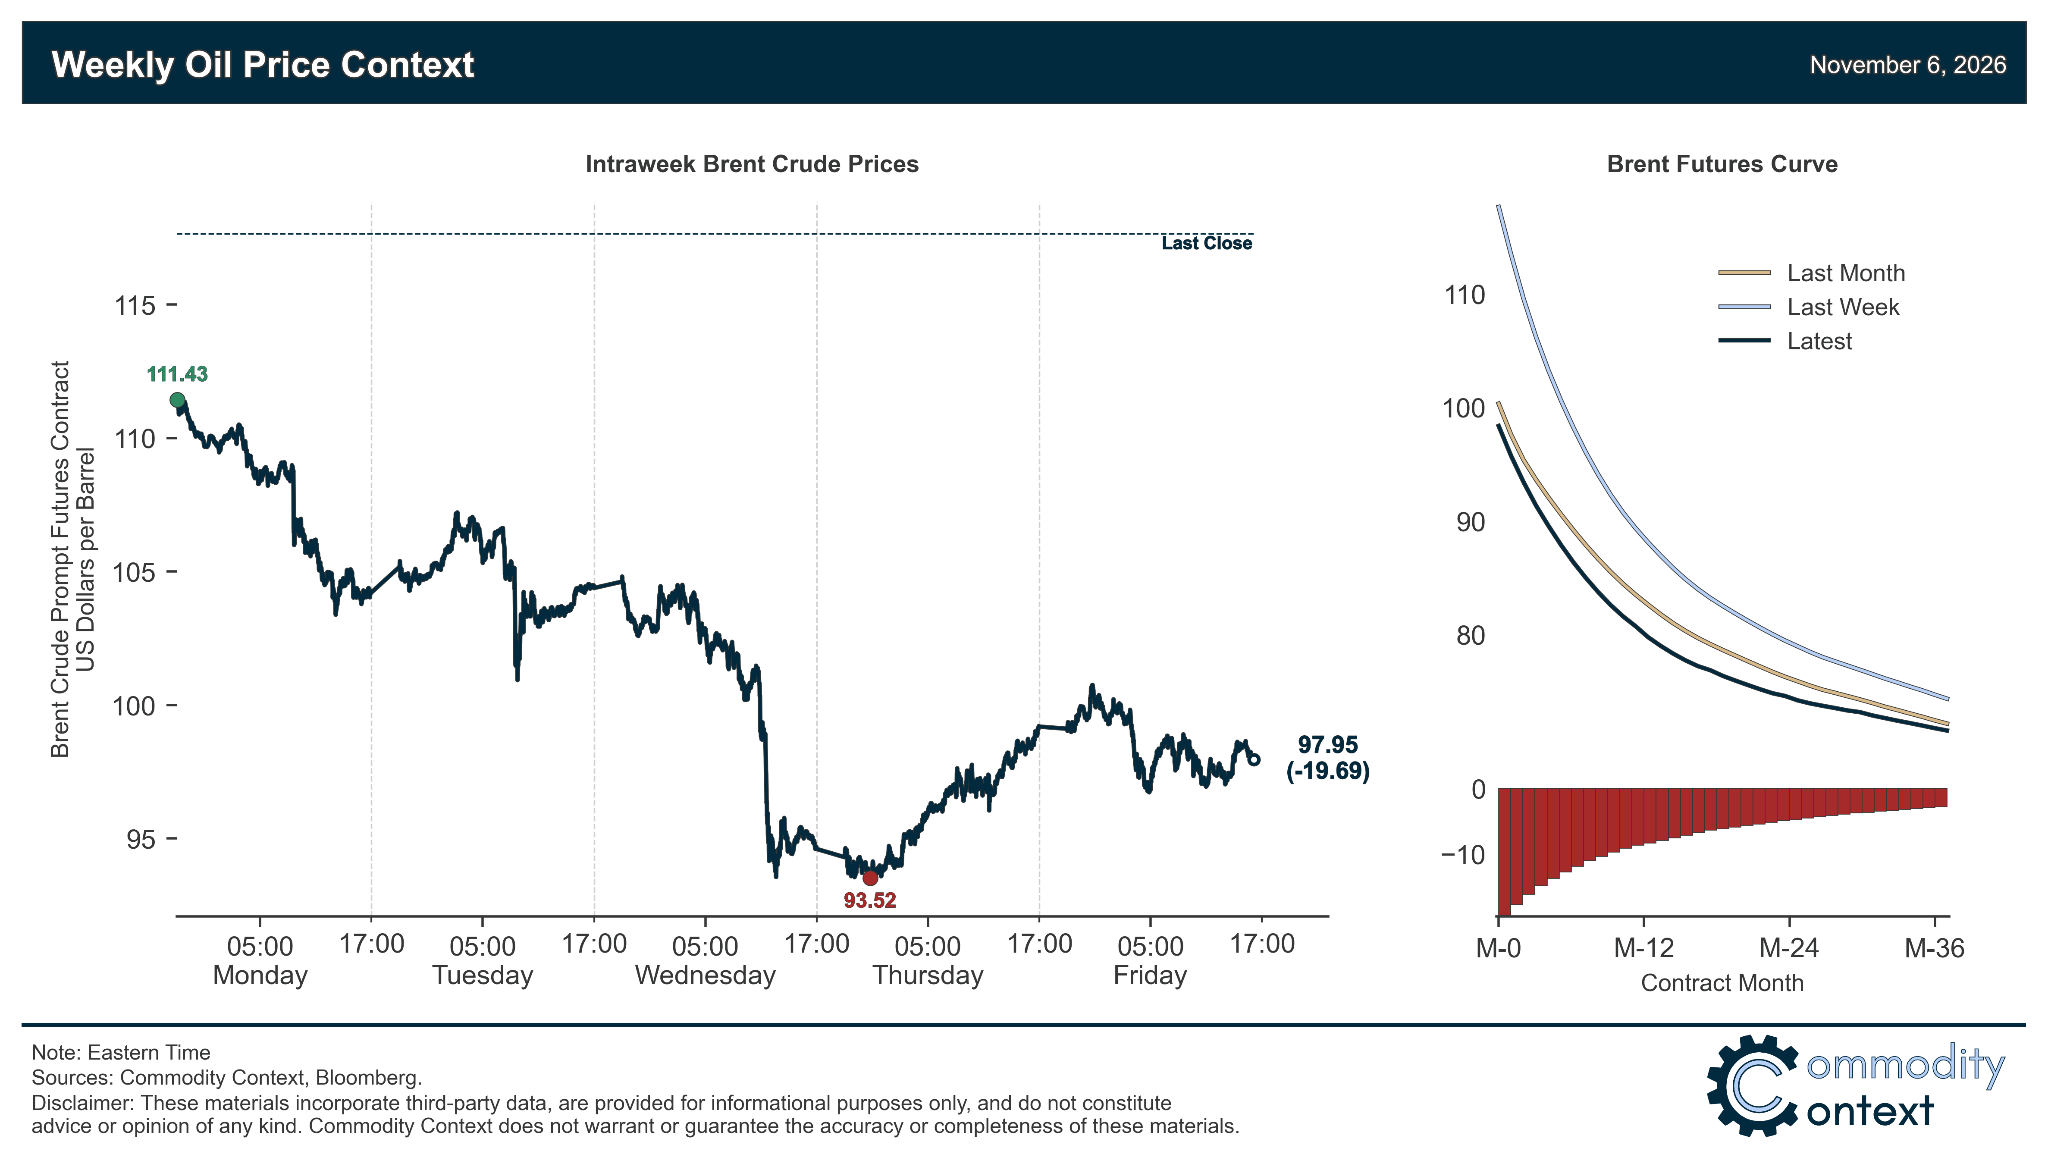
Flat Prices fell roughly $20/bbl for prompt Brent futures, the largest weekly decline since mid-April, as markets pulled back first on weekend hedges in the absence of pre-Midterm strikes and then on a landslide Democratic victory in the midterms, with hope that the demonstrated unpopularity of the Iran War decreases the odds of escalation.
Timespreads traded flat to lower, though were far more resilient than the rout experienced in flat prices; while futures backwardation remained well entrenched, the front few weeks of the Brent CFD curve are in contango and currently represent the most worrying downside signal for crude markets.
Inventories data leaned bullish given a large US draw, deeper into fresh seasonal lows; a small Singaporean draw, to seasonal lows; and a moderate ARA European build, from exceptionally low seasonal levels to just still-very-low seasonal levels. All major product categories across all tracked regions are at or below the bottom of trailing 5-year seasonal lows.
Refined Products markets are still squarely focused on diesel, cracks for which continue to bounce around the low-$80s in New York Harbor (vs. Brent); while still ~4x their normal levels, they’re down ~$30/bbl from September highs, with the decline supported by: (1) a Russian diesel export rebound, (2) a fourth top-up to export quotas for Chinese independent refineries, and (3) ratcheting higher Indian middle distillate exports.
Market Positioning data confirmed the largest speculative selling week since mid-June amidst the post-MOU rout, with hedge funds and other money managers reducing their net position by 78 million barrels over the past week-through-Tuesday. While net spec positions are now at the bottom of our trailing 3-month experience, there’s plenty of room to the downside of July’s low and we still only have modest short interest driving this latest selloff.
As Well As Democrats sweep Midterm elections; a deep dive into current Iran War escalation risk; Stephen Miller elevated to Trump’s Chief of Staff; Iranian shipping attacks re-escalate; and Indian petroleum demand growth returns.