

Happy Friday, and wishing you all a spooky Halloween weekend, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
🎙️ On the latest episode of the Oil Ground Up podcast (YouTube), I was joined by Dennis Kissler, Senior Vice President and head of trading at BOK Financial, a major counterparty for US oil and gas producers looking to hedge their price risk. Our conversation focused on what it’s like to hedge client barrels in this market and how to, more broadly, manage risk in our current, volatile geopolitical situation.
📺 For more public oil market context, check out my long-form conversations on The Great Simplification Podcast (YouTube), with Atrioc (YouTube), and the American Power podcast (YouTube), as well as my comments to Reuters’ Ron Bousso on Canada’s strategic pipeline ambitions (Print).
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
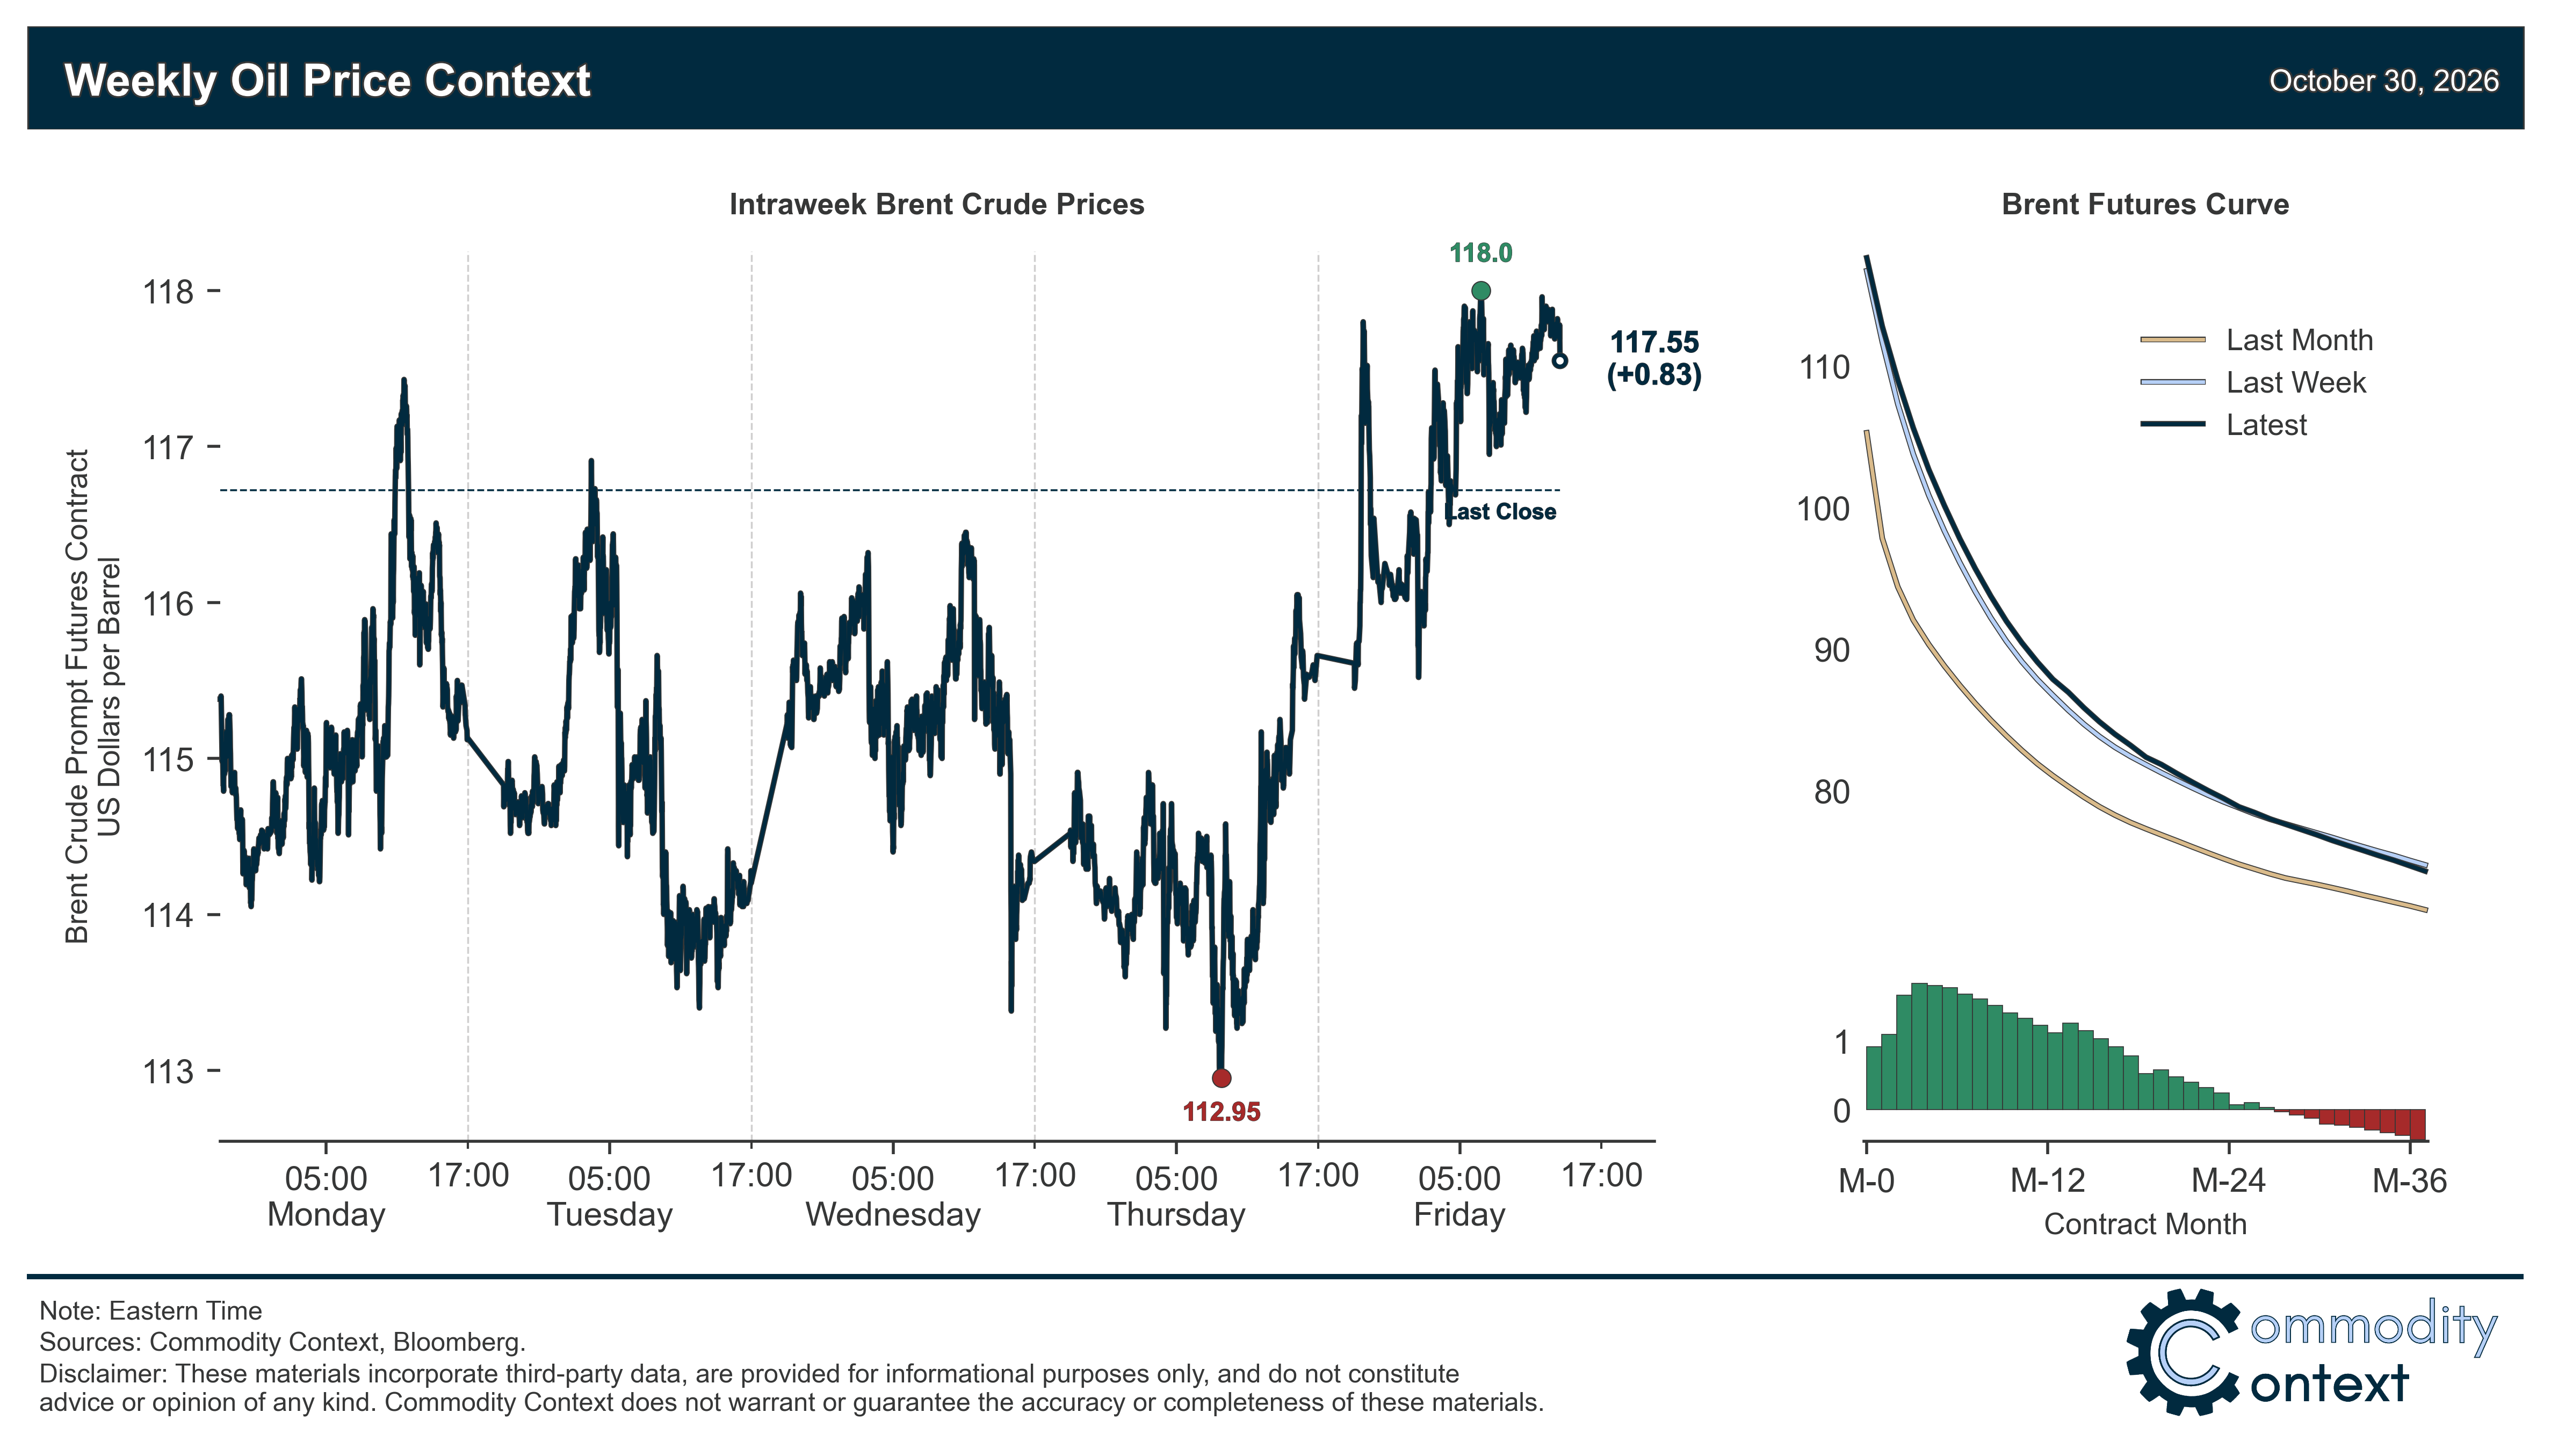
Flat Prices ended at just below $118/bbl (prompt Brent), the third highest close of the war for the global crude oil benchmark as markets braced for any weekend surprises ahead of the US Midterm elections on Tuesday.
Timespreads pulled back again—particularly for Brent—but retained broadly prompt-backwardated across all major crude benchmarks, painting a modestly less urgent but still scarce supply environment; a late-week dip into mild Brent CFD (next couple of weeks) contango is a potential warning sign that demand is beginning to wane.
Inventories data were far less dramatic than last week, showing moderate draws across the US and ARA Europe coupled with a small build in Singapore; stocks at or below trailing seasonal lows leaves the world with few buffers ahead of both the winter and any potential Middle Eastern reescalation.
Refined Products markets continue to be dominated by diesel, which eased but cracks remain at 4-fold the seasonal norm; diesel margins have fallen ~$15/bbl over the past nine days largely on the hope of additional Russian middle distillate barrels amidst a pause in Ukrainian refinery strikes—though Ukraine resumed attacks last night.
Market Positioning data revealed that speculative participants were small net sellers of crude futures and options contracts over the past week-through-Tuesday but both gross short and long positions declined as market participants pulled back ahead of the midterm wildcard.
As Well As Hormuz oil flow rebounds before dipping again amidst mounting attacks and escalatory fears, Canadian heavy oil prices at tidewater hit with highest discount on record, and US awards final tranche of authorized Strategic Petroleum Reserve release as outflow dwindles to a trickle.