

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
For more public oil market context, check out my appearances on War on the Rocks’ Warcast (audio), The Financial Times’ Economics Show with Soumaya Keynes (audio), and Real Vision’s Geopolitical Edge (video).
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
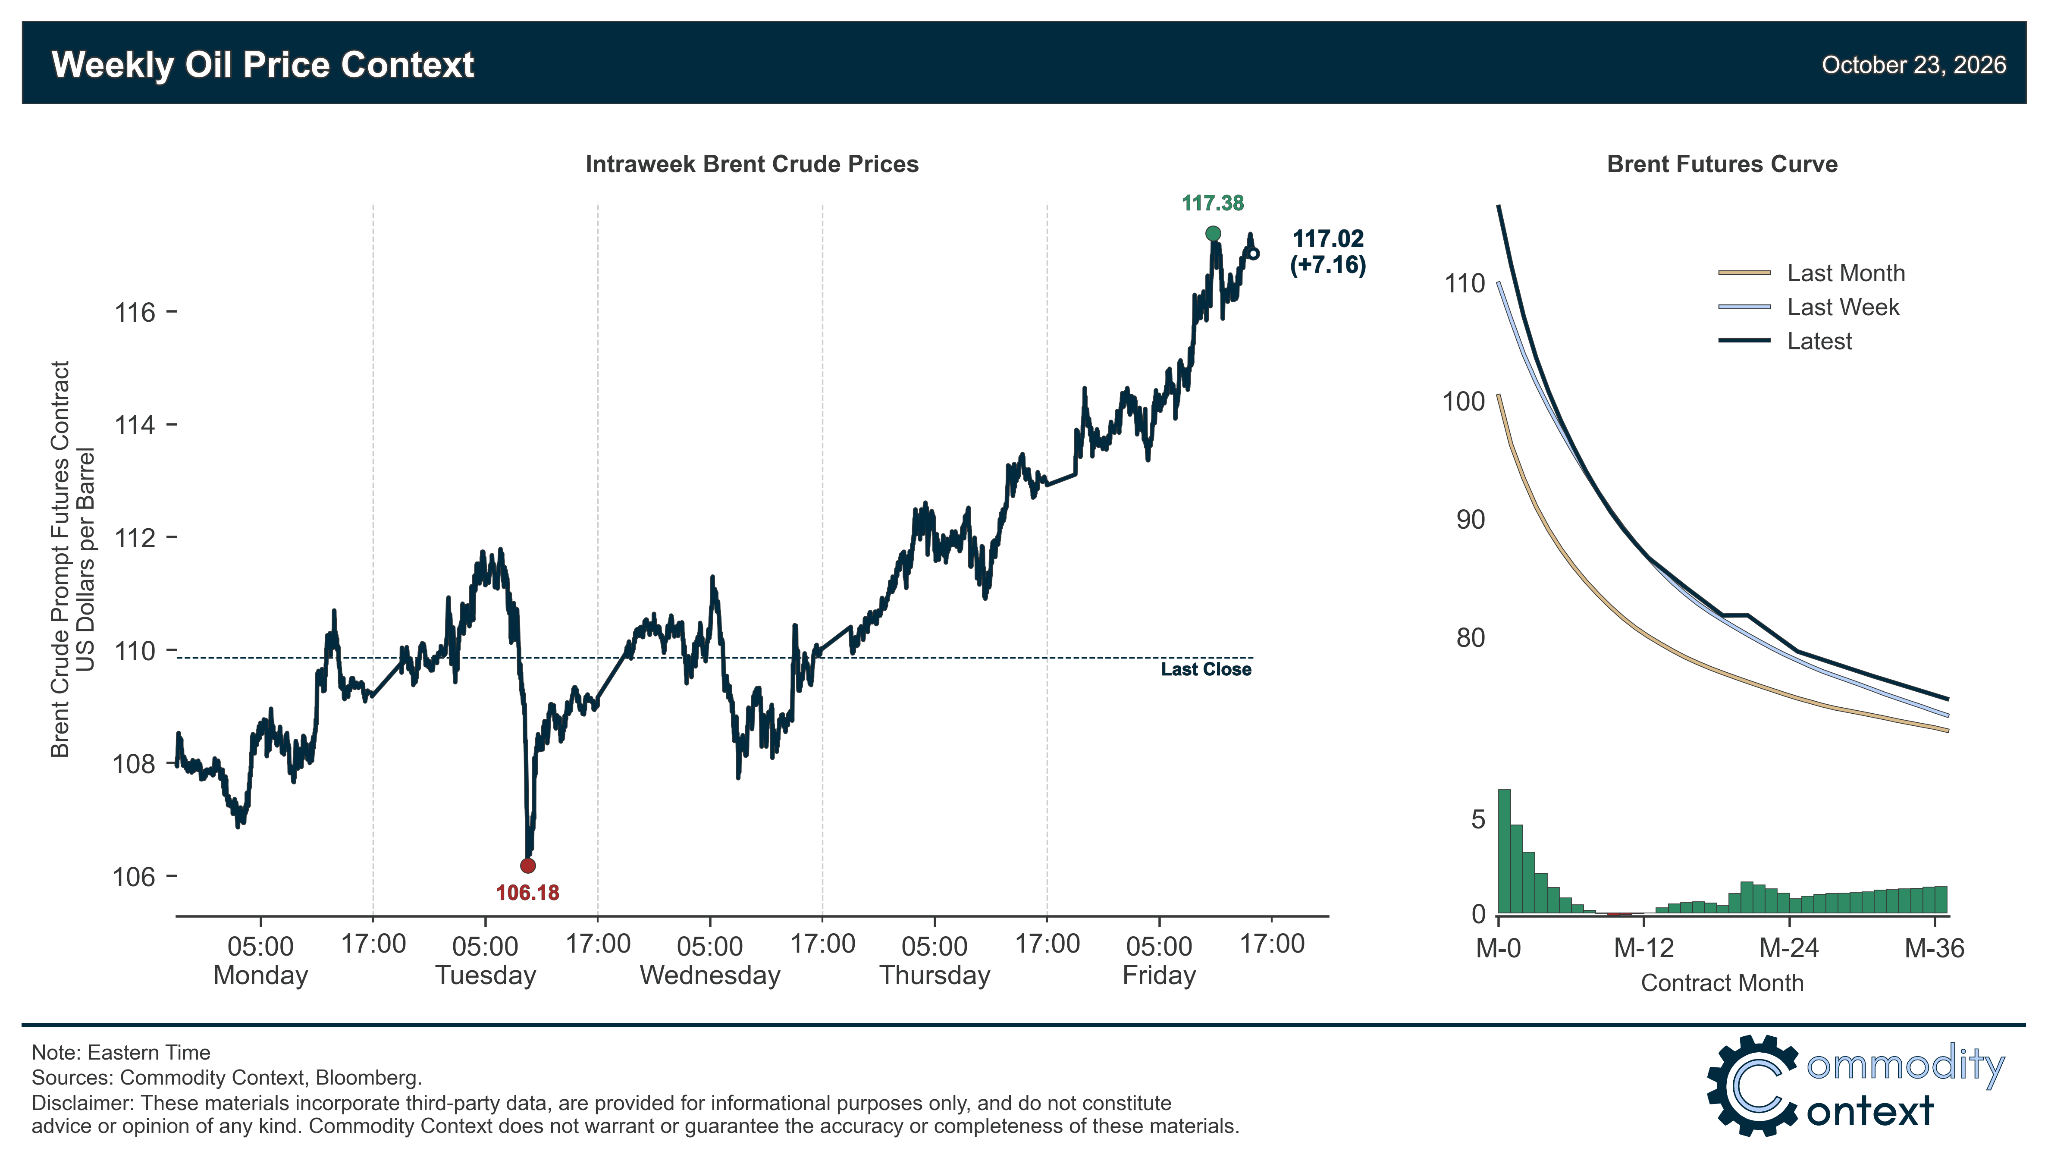
Summary
Flat Prices rose nearly $7/bbl for Brent crude to end the week around $117/bbl, higher than all but two daily closes in March and April, as markets begin to price in the expectation of kinetic reescalation after the US midterm elections and, more broadly, the messy reality of this “new normal”.
Timespreads saw prompt backwardation steepen across all major crude benchmarks as Brent and Dubai saw prompt premiums rise by two-thirds to around $5/bbl and Brent DFLs nearly double to nearly $10/bbl; WTI prompt backwardation only rose ~50c to $2.50/bbl, albeit after an especially explosive November contract settlement on Tuesday that briefly spiked to $9/bbl.
Inventories data confirmed across-the-board headline draws for the US, Singapore, and ARA Europe, with all three regions showing all major product categories at or below trailing 5-year seasonal lows.
Refined Products pulled back as diesel eased to still-absurdly-high levels following news of a release from the US Northeast heating oil reserve and a welcome build in US weekly stocks; similarly, gasoline crack spreads fell to the lowest level since the beginning of the Iran War and within a few bucks of the seasonal average.
Market Positioning data confirmed that speculators were modest net buyers of crude over the past week-through-Tuesday, though that increase in net position was driven overwhelmingly by the ongoing capitulation of gross shorts.
As Well As real geopolitical risk premium returning to the barrel, Iran War looks set to re-escalate after US midterm elections, Saudi-Houthi war also continues to worsen, and Chinese crude oil imports tentatively recover to 2025 levels and help maintain bid for crude despite rising Middle Eastern export flow.