

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
On the latest episode of the Oil Ground Up podcast (YouTube), I was joined by the one and only Javier Blas, long-time oil watcher, Bloomberg Opinion columnist covering energy and commodities, and co-author of The World for Sale: Money, Power, and the Traders Who Barter the Earth’s Resources. Our sweeping conversation looked at the evolution of commodity trader risk tolerance through the fog of war; what’s happening in the Strait of Hormuz and the broader Gulf; how record tanker rates are balkanizing a previously global oil market; the unique and impossible to understate role of China through the crisis; and how OPEC may be reconsidering its future in light of current events.
For more public oil market context, check out my long conversation with Drop Site News’ Ryan Grim (YouTube) and with Mario Nawfal (YouTube) about Trump’s oil market heading into the midterm elections in a few weeks. I also spoke with Bloomberg News (print) about the perfect storm of factors—from exploding shipping rates to weak USGC fuel oil markets—currently standing between Canadian oil producers and their ability to take advantage of high global crude prices, which I expand upon in the report below. As I said to Bloomberg, “Generally, it’s all bad news for Canadian oil.”
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
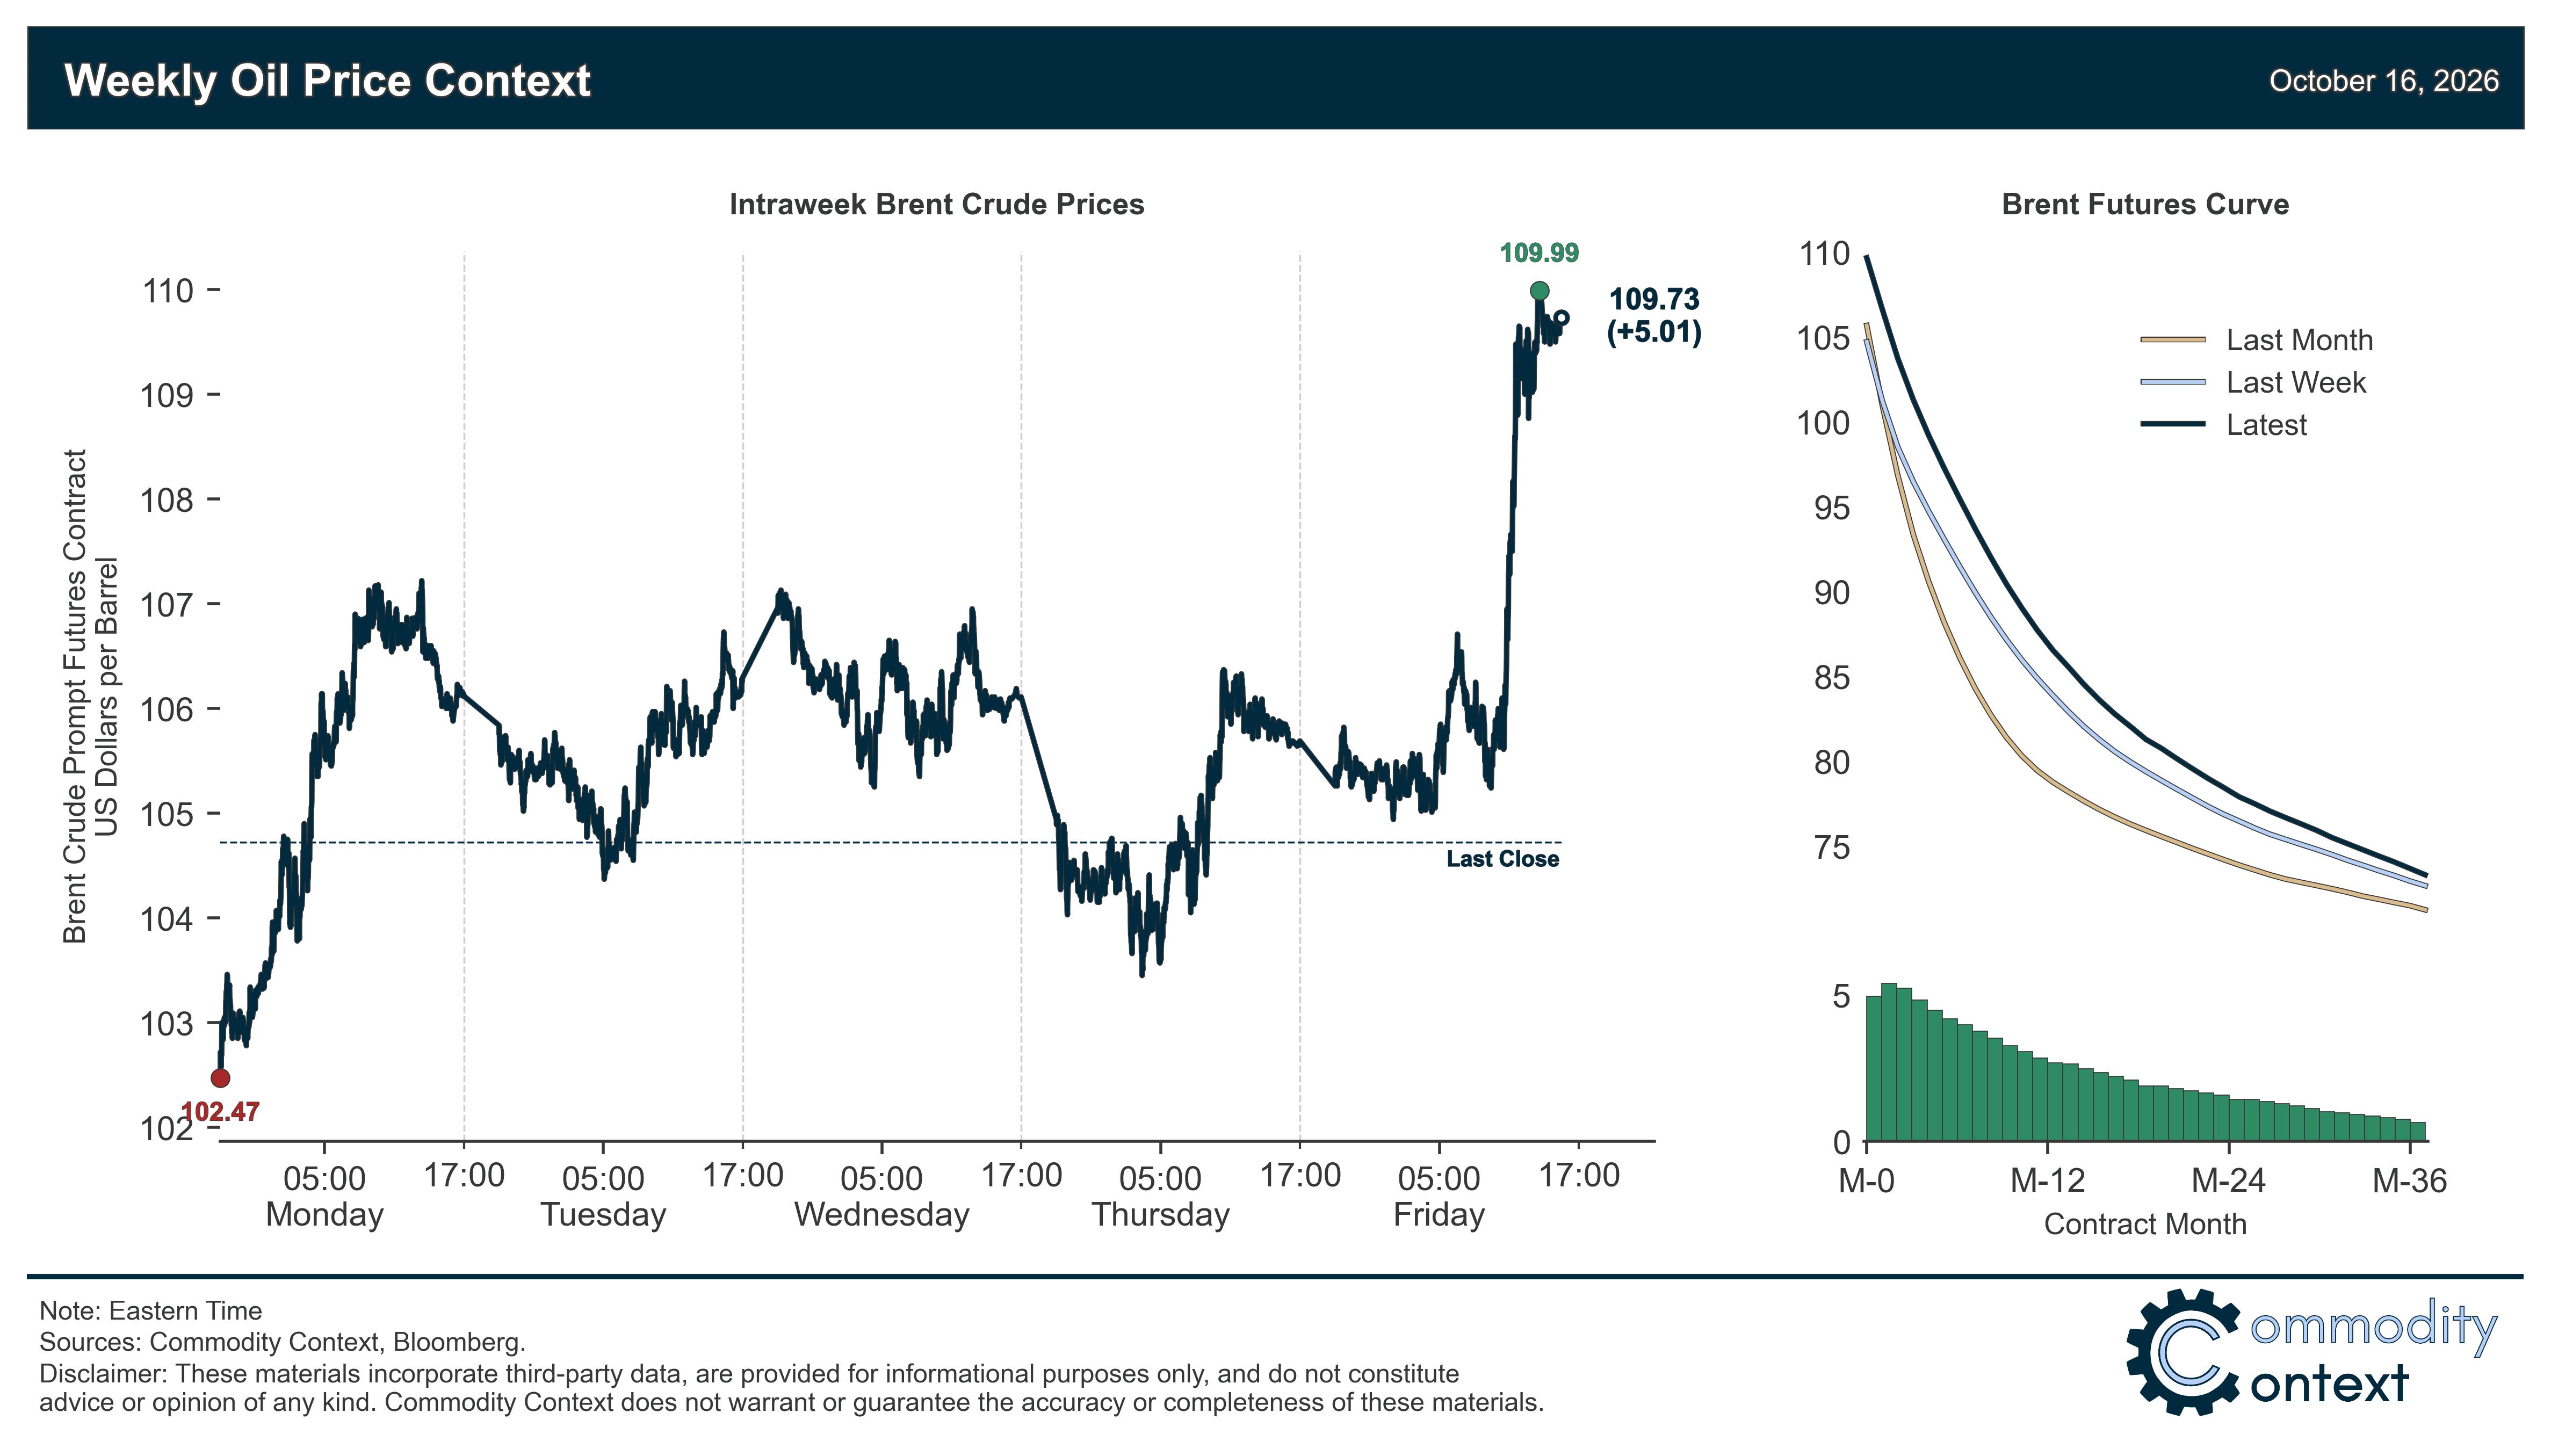
Flat Prices rose roughly $5/bbl for Brent to finish around $110, briefly popping above that level for the first time since May in a furious Friday rally amid rumours of renewed damage to Saudi infrastructure and rapidly proliferating concerns that both the US-Iran and Saudi-Houthi conflicts could escalate imminently.
Timespreads performance was split through most of the week between easing backwardation across Brent and Dubai juxtaposed against strengthening backwardation in WTI prompt spreads; however, everything rallied hard together on Friday. While normally a clear sign of firm physical market strength, this latest re-strengthening of futures backwardation should be tempered by the sharp and contemporaneous $10/bbl decline in the price of Dated Brent.
Inventories data leaned bullish on the back of a large, hurricane-driven draw in US inventories; both ARA European and Singaporean stocks built from still-depressed levels.
Refined Products markets are still dominated by hyper-tight middle distillate markets that are keeping crack spreads around $100/bbl despite the White House pulling every imaginable lever ahead of the midterms; gasoline cracks have fallen steadily through October, though remain at more than double seasonal levels.
Market Positioning data confirmed that speculators were modest net buyers of crude futures and options contracts, with the net spec position sitting at the high end of recent experience as a share of total open interest across the six largest crude contracts; Friday’s sharp rally likely indicates that further hot money poured in (or shorts covered) ahead of the weekend.
As Well As Strongest pace of Hormuz shipping attacks thus far depresses oil flows and tempts US retaliation; the perfect storm weakening Canadian crude prices; and Russia’s diesel commitment complications (spoiler: Ukraine hit two more Russian refineries over the past 24 hours)