

Happy Friday, Oil Watchers!
Every week, I summarize and analyze developments in flat crude prices, calendar spreads, high-frequency inventories, refined products, and positioning data, as well as a taste of the themes I’ve been thinking about or following closely—including our ongoing tracking of shipping flows throughout the Middle East.
Paid subscribers can access the latest weekly update of the detailed 40-page PDF Market Positioning Data Deck at the bottom of this report.
If you’re already subscribed and/or appreciate the free chart and summary, hitting the LIKE button is one of the best ways to support my ongoing research.
Summary
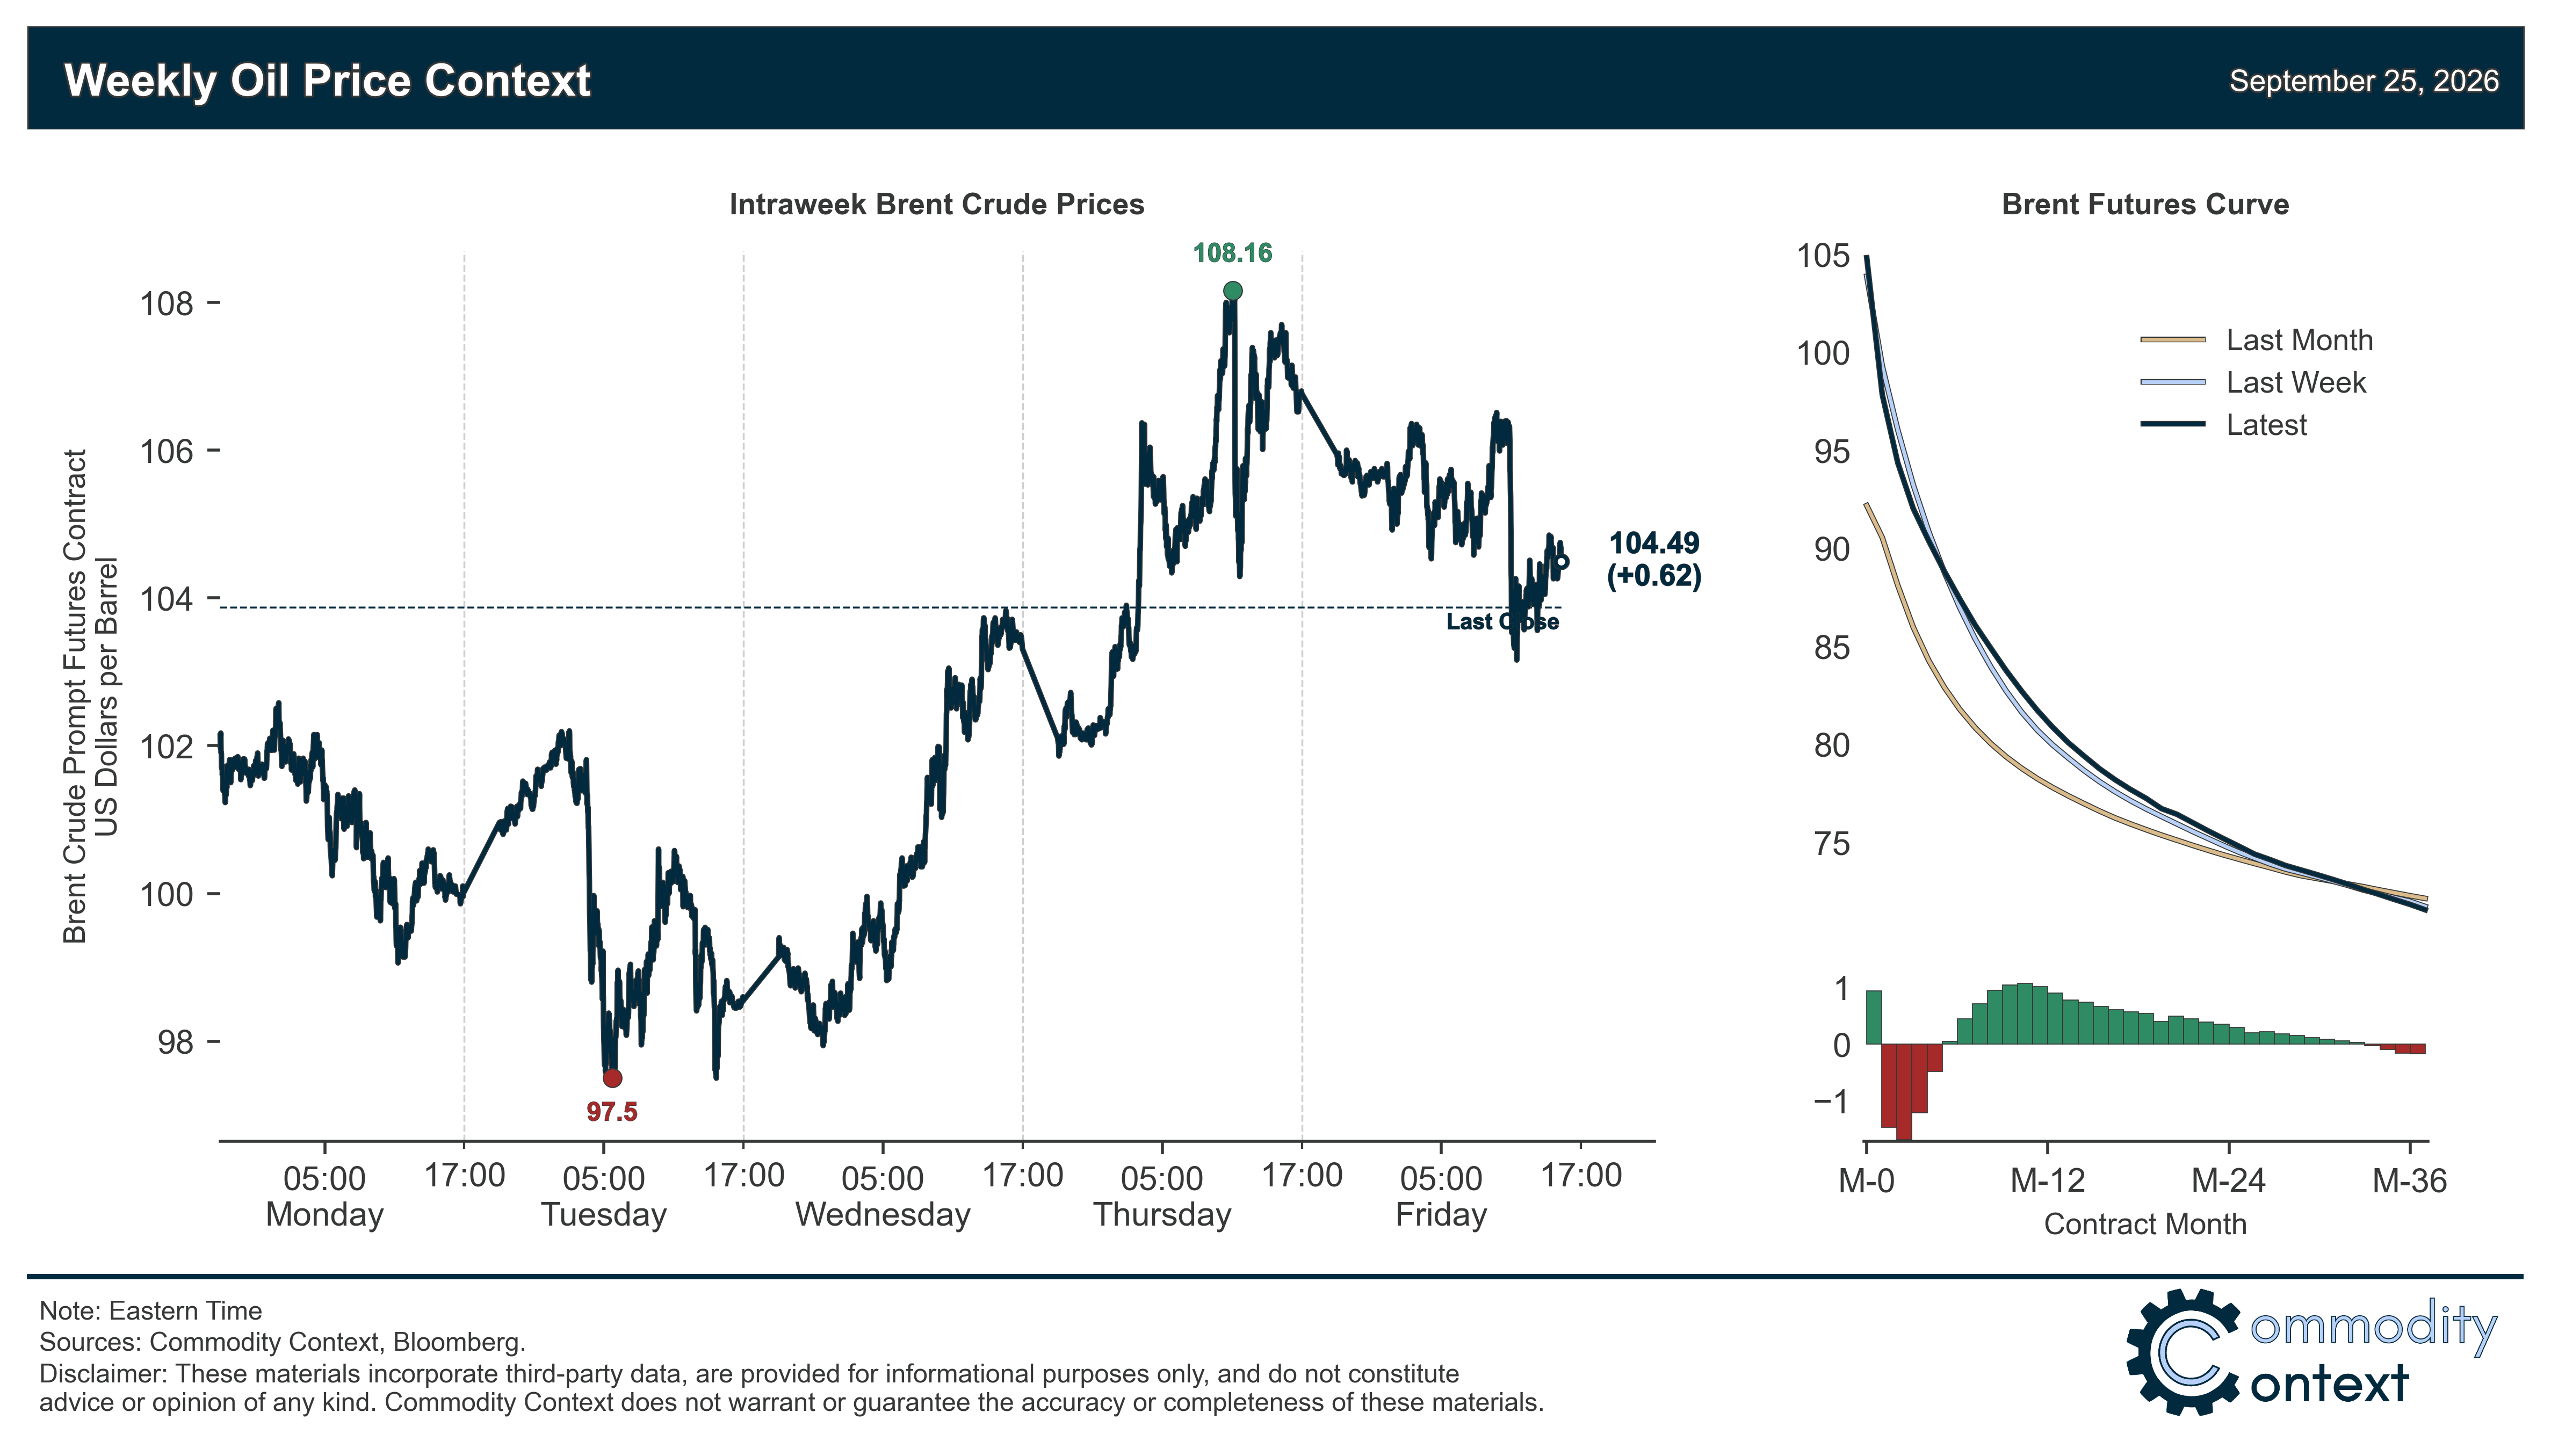
Flat Prices again ended the week more or less flat, up less than $1/bbl; contracts started the week under further downside pressure stemming from further US-Iran diplomatic optimism, before they rallied through Thursday on the same diplomatic roadblocks as always together with renewed concerns regarding physical crude scarcity.
Timespreads ratcheted higher across crude grades but the gain was sharpest in Brent, which saw prompt futures spreads rise by ~50% to around $7/bbl while DFLs doubled from Tuesday’s lows to more than $10/bbl; crude markets continue to signal mounting scarcity despite the rising flow of oil from Hormuz, reflecting both the loss of Red Sea supplies and rising import appetite despite higher prices heading into winter.
Inventories data was mixed between flat headline stocks (crude up, products down), a moderate crude-driven build in still-depressed ARA European stocks, and a sharp decline in Singaporean inventories that entirely unwound the prior week’s steep build in light distillate stocks.
Refined Products markets loosened notably this week from last week’s extreme heights; US diesel crack spreads fell back by ~$20/bbl and gasoline followed suit, shedding more than $10/bbl from mid-week crack-highs; some of the pullback was driven by headlines this week that indicated that the White House was warming to the idea of a diesel export ban, but European gasoil crack spreads also pulled back by ~$15/bbl indicating a broader easing of middle distillate scarcity concerns on the week.
Market Positioning data confirmed that speculators were moderately large net sellers of crude futures and options contracts over the past week-through-Tuesday,
As Well As a US-Iran diplomatic optimism merry-go-round at the UN General Assembly, the White House awkwardly lurches toward a diesel export ban, and cracks emerge as the Beijing Swing ages.